
Hyperliquid Funding Rates Explained: Hourly Formula, Caps, Oracle vs Mark Price, Open Interest and Volume (2026)
Hyperliquid funding rates explained: hourly formula, 0.01% base rate, 4%/hour cap, oracle vs mark price, open interest, volume and how to earn from arbitrage.
Understanding Hyperliquid funding rates lets you avoid paying for crowded positions and even earn from them: funding is paid every hour between longs and shorts to keep each perpetual's price pinned to its oracle price. The rate is computed from the perp's hourly average premium plus a 0.01% per-8-hour base rate, paid at one eighth of the 8-hour figure each hour, and capped at 4% per hour. Positive funding means longs pay shorts, negative means shorts pay longs. Our guide explains the formula, the oracle-versus-mark distinction, how to read Hyperliquid open interest and volume, where to find the data (app, Coinglass, Hyperdash, DefiLlama, API), typical funding regimes and the basics of funding arbitrage.
Key takeaways
- Your perp tracks its index more tightly because funding is hourly on Hyperliquid, not every 8 hours as on most CEXs; rates are quoted as 8-hour equivalents and paid at 1/8 each hour.
- You can verify every payment yourself with the formula: premium relative to the oracle price plus a clamped interest component around a 0.01% per 8h base rate; hourly payments are capped at 4%.
- You are shielded from single-trade liquidations: the oracle price (CEX spot median) drives funding, while the mark price (oracle + book + external perps) drives liquidations and P&L.
- You can read positioning from open interest, the total notional of open positions: rising OI with rising price signals new longs, rising OI with falling price signals new shorts.
- You trade in the deepest on-chain books: Hyperliquid daily volume is $5–15 billion as of September 2026, the largest on-chain; OI typically $8–15 billion.
- Every dollar of funding goes to the other side of the trade; the protocol keeps none of it.
Hyperliquid funding rates: why perps need funding
Funding is what keeps the perp you hold priced close to the real asset, because a perpetual future has no expiry to force convergence. When the perp trades above the oracle price, longs pay shorts, making it costly to stay long and attractive to short until the gap closes; when the perp trades below, shorts pay longs. Hyperliquid runs this mechanism for every perp on the platform, from BTC and HYPE to HIP-3 markets like XYZ100, NVDA and WTI crude.
Two design choices set Hyperliquid apart. First, funding settles every hour, which keeps the perp much closer to its index than 8-hour cycles do and reduces the "funding sniping" seen on exchanges where traders open positions seconds before settlement. Second, funding is computed from on-chain data (the order book's impact price versus a validator-provided oracle), so anyone can verify it.
The Hyperliquid funding formula
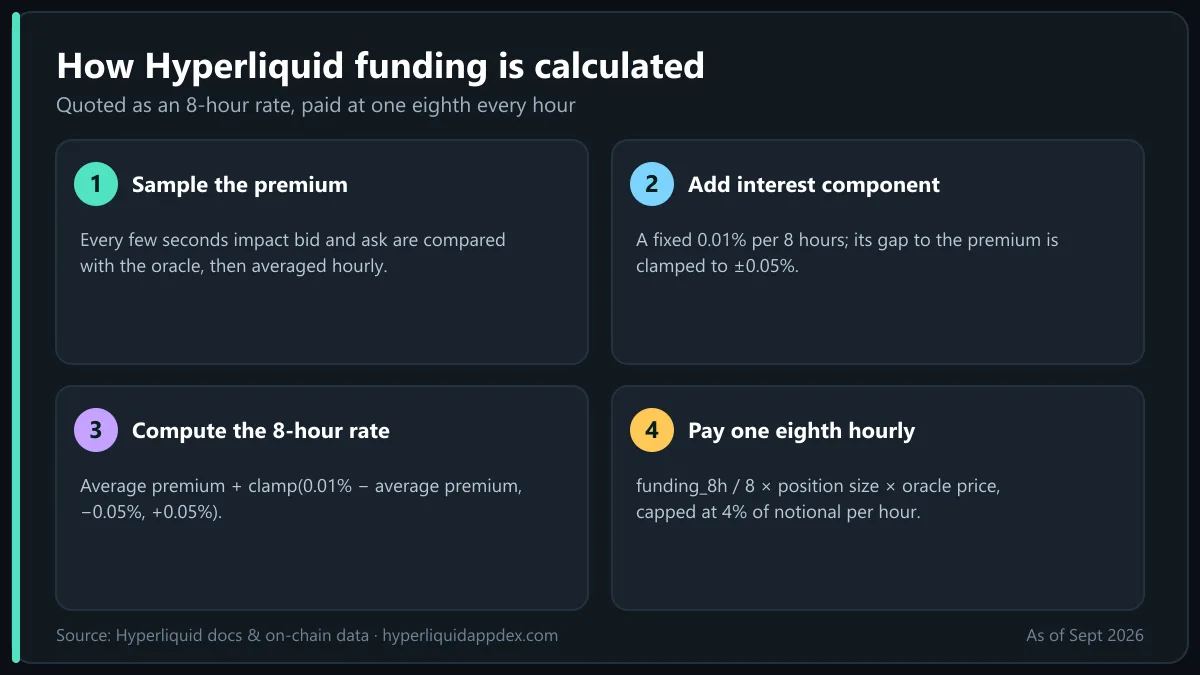
You can reproduce every funding payment from four steps, because Hyperliquid follows the same premium-and-interest structure as major exchanges, adapted to hourly payment.
Step 1: Premium. Every few seconds the engine samples the impact bid and impact ask prices (the average execution price for a fixed notional, so a few tiny orders cannot skew it) and computes:
premium = (max(impact bid − oracle, 0) − max(oracle − impact ask, 0)) / oracle
Over the hour these samples are averaged into the average premium index.
Step 2: Interest component. A fixed interest rate of 0.01% per 8 hours represents the cost of holding the quote asset versus the base asset. The difference between the interest rate and the premium is clamped to ±0.05%.
Step 3: 8-hour funding rate.
funding_8h = average premium + clamp(0.01% − average premium, −0.05%, +0.05%)
Step 4: Hourly payment.
hourly payment = (funding_8h / 8) × position size × oracle price
capped so that no single hour exceeds 4% of notional in either direction.
Worked example: BTC trades at an average 0.04% premium to its oracle during the hour. funding_8h = 0.04% + clamp(0.01% − 0.04%) = 0.04% − 0.03% = 0.01%. Hourly rate = 0.01% / 8 = 0.00125%. A $100,000 long pays $1.25 for that hour. If the premium spikes to 0.5%, the clamp binds at −0.05%, funding_8h = 0.45%, hourly = 0.05625%, and the same long pays $56.25 per hour, roughly $1,350 a day.
Notice that when the market is perfectly balanced (premium = 0), funding settles at the base rate of 0.01% per 8h, or about 0.00125% per hour, paid by longs. Over a year that is roughly 11%, which is why "neutral" funding still slightly favors shorts.
How funding hits your account
You see every payment land in your margin at the top of each hour, listed in the Funding tab. On an isolated position, paid funding reduces margin and nudges your liquidation price toward the market; received funding does the opposite. On cross, it flows through account value. See how this interacts with liquidation math in the Hyperliquid liquidation price guide.
Hyperliquid oracle price vs mark price
Knowing which of the two reference prices does what saves you from real losses.
| Oracle price | Mark price | |
|---|---|---|
| Source | Validator-weighted median of spot prices from Binance, OKX, Bybit, Coinbase, Kraken, Gate, MEXC, etc., updated ~every 3 seconds | Median of (oracle + 150s EMA of book-mid minus oracle), Hyperliquid's own best bid/ask/last, and a median of external perp mid prices |
| Used for | Funding rate computation, HIP-3 stock/commodity index | Liquidations, unrealized P&L, TP/SL triggers, margin checks |
| Can a single trade move it? | No | Only marginally, because it is a blended median |
| Where to see it | Market info panel, metaAndAssetCtxs API |
Positions tab, same API |
The Hyperliquid oracle is deliberately external: it reflects where the asset trades on the broader market, not on Hyperliquid alone. That is what makes funding meaningful, since the premium measures Hyperliquid's perp against the world's spot price. For HIP-3 markets the deployer supplies the oracle (for example, equity prices from licensed data feeds for NVDA or index calculations for XYZ100), and during off-hours the oracle holds the last close or uses proxy inputs, which is why funding on stock perps can widen sharply on weekends.
The mark price protects you from manipulation. Because it blends the oracle with the book's EMA and external perp prices, a whale slamming the Hyperliquid book cannot liquidate you unless the wider market moves too. Hyperliquid tightened these safeguards after the JELLYJELLY manipulation attempt in March 2025.
Reading Hyperliquid open interest
Reading open interest (OI) tells you whether a move is backed by fresh money or by forced exits. OI is the total notional value of all open positions on a market, counted once per matched long/short pair. Hyperliquid's platform-wide OI has typically sat between $8 billion and $15 billion as of September 2026, with BTC, ETH, SOL and HYPE accounting for most of it.
How to interpret changes:
| Price | Open interest | Interpretation |
|---|---|---|
| Rising | Rising | New longs entering; trend supported by fresh money |
| Rising | Falling | Shorts covering; rally may lack fuel once covering ends |
| Falling | Rising | New shorts entering; downtrend supported |
| Falling | Falling | Longs liquidating or exiting; capitulation phase |
Combine OI with funding: rising OI plus sharply positive funding means crowded longs and elevated liquidation cascade risk; rising OI with negative funding means crowded shorts and squeeze potential. The liquidation heatmaps on Coinglass and Hyperdash, covered in our Hyperliquid margin guide, show where those crowded positions would be forced out. For reading those clusters level by level, see the Hyperliquid liquidation map guide.
OI is also capped per market by the protocol: when a perp's open interest reaches its cap, only reduce-only orders are allowed until it falls. Caps are visible in the market info panel and are one of the tools used to keep illiquid perps from becoming systemic.
Hyperliquid volume: daily, 24h and share
You get the tightest spreads on-chain because Hyperliquid daily volume for perps has commonly ranged from $5 billion to $15 billion in 2025–2026, with single-day peaks above $20 billion during major volatility. Spot volume adds several hundred million to a few billion a day. At its peak Hyperliquid held 70%+ of all on-chain perp volume; competition from Lighter and Aster has pulled that share down at times, but it remains the largest venue by a wide margin (see Hyperliquid vs Lighter and Hyperliquid vs Aster).
Why volume matters beyond bragging rights:
- Fees and buybacks. Roughly 0.02–0.03% of volume is collected as net fees, so a $10 billion day yields about $2.5–3 million, nearly all of which the Assistance Fund spends buying HYPE. This is the link between "hyperliquid 24h volume" and the token; see our Hyperliquid valuation guide.
- Liquidity. High volume means tighter spreads and lower slippage for your orders, which usually outweighs fee differences between venues (details in the Hyperliquid fees guide).
- Volume-to-OI ratio. Volume / OI around 1 signals mostly intraday churn; well below 1 indicates positions being held; a spike in volume with flat OI often marks a liquidation flush.
Where to see Hyperliquid funding, OI and volume
You can get every number below without paying for data. In the Hyperliquid app, hover the info icon on any market for funding rate (shown as an 8-hour rate and countdown to next payment), open interest, oracle and mark prices, and 24h volume. The Funding tab under your positions lists every payment you have made or received. The stats page summarizes platform-wide volume and OI.
Coinglass Hyperliquid pages. Coinglass tracks funding across exchanges in a single table, letting you compare Hyperliquid's BTC rate with Binance, Bybit and OKX at a glance, plus OI, liquidations, a liquidation heatmap and the Hyperliquid whale tracker that follows addresses such as 0xb317….
Hyperdash. Hyperliquid-native analytics with per-market funding history, OI by asset, long/short ratios, whale positions and HLP exposure.
DefiLlama. Daily and cumulative volume, fees, revenue and TVL for Hyperliquid on DefiLlama, the easiest place to verify aggregate claims.
Hypurrscan and Dune. Wallet-level history and community dashboards.
The API. metaAndAssetCtxs returns live funding, OI, oracle and mark per asset; fundingHistory returns hourly history; predictedFundings compares Hyperliquid's next rate with Binance and Bybit; and the WebSocket activeAssetCtx subscription streams updates. Examples are in the Hyperliquid API docs guide.
👉 Open the Hyperliquid app and save 4% on fees
SIXPROSPERHyperliquid funding rate history: where to download it
You can pull Hyperliquid funding rate history for taxes, backtests or sanity checks with one extra step, depending on what you need.
Your own payments. In the app, open Portfolio, then the Funding tab. Every hourly payment you have made or received is listed with market, position size, rate and USDC amount, and the Export button downloads the table as CSV for tax or P&L work.
Per-market history via the API. The /info endpoint accepts {"type":"fundingHistory","coin":"BTC","startTime":<ms>,"endTime":<ms>} and returns one record per hour with fundingRate (the hourly rate as a decimal), premium and time. Responses are capped at 500 records, so a full year of BTC funding needs about 18 paginated calls; set startTime to the last time you received and loop. Multiply the hourly figure by 8 to compare with the 8-hour rates quoted on CEXs, or by 24 x 365 for an annualised number. The Hyperliquid API guide has the Python pattern. The Hyperliquid SDK wraps the same call in its Info client so you do not build the request by hand.
Charts without code. Coinglass plots Hyperliquid funding rates history per market alongside Binance and Bybit, and lets you switch between hourly, 8-hour and daily aggregation. Hyperdash shows the same series per asset with open interest overlaid, which is useful for spotting the squeezes described below. Dune dashboards built on the funding tables let you query cross-market averages or the long-run mean for a coin.
What the history is good for. Backtesting carry trades, checking how extreme a current rate is relative to the past year, and verifying your own Funding tab against chain data. Protocol-wide funding is not revenue, so you will not find it on DefiLlama.
Typical Hyperliquid funding regimes
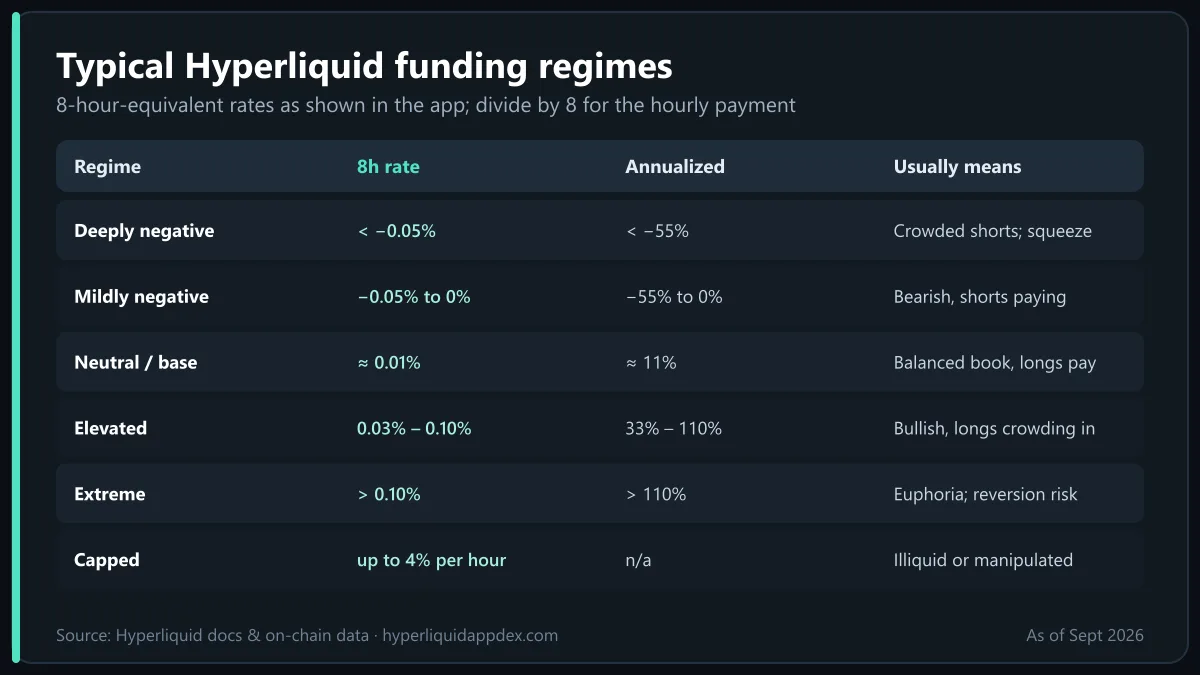
Recognizing the regime you are in tells you whether holding is cheap or costly. The table uses 8-hour-equivalent rates, which is how the app displays them; divide by 8 for the hourly payment and multiply by roughly 1,095 for a crude annualized figure.
| Regime | 8h rate | Hourly | Annualized (approx.) | What it usually means |
|---|---|---|---|---|
| Deeply negative | < −0.05% | < −0.006% | < −55% | Crowded shorts after a crash; squeeze risk |
| Mildly negative | −0.05% to 0% | −0.006% to 0% | −55% to 0% | Bearish sentiment, shorts paying |
| Neutral / base | ≈ 0.01% | ≈ 0.00125% | ≈ 11% | Balanced book; base rate paid by longs |
| Elevated | 0.03% – 0.10% | 0.004% – 0.0125% | 33% – 110% | Bullish, longs crowding in |
| Extreme | > 0.10% | > 0.0125% | > 110% | Euphoria, new listings, meme coins; mean-reversion risk |
| Capped | up to 4% per hour | 4% | n/a | Illiquid or manipulated market; effectively closes the gap fast |
Patterns worth knowing as of September 2026:
- BTC and ETH spend most of their time between 0.005% and 0.03% per 8h. Sustained readings above 0.05% have historically preceded pullbacks.
- HYPE funding runs hotter than majors because holders use the perp to lever up on the token.
- New listings and memes frequently print 0.1%–1% per 8h in their first days, which is where the 4% hourly cap becomes relevant.
- HIP-3 stock perps show funding spikes ahead of earnings and over weekends when the oracle is stale relative to news; commodity perps like gold and oil follow their futures curves more calmly. See Hyperliquid TSLA and Hyperliquid WTI market pages.
Funding arbitrage on Hyperliquid
You can turn funding into income with a delta-neutral position, because it is a payment from one side to the other. The basic cash-and-carry trade:
- Buy the asset on spot (Hyperliquid spot for HYPE, PURR or Unit-bridged BTC/ETH/SOL, or on any exchange).
- Short the same notional on the Hyperliquid perp.
- Collect positive funding every hour while price exposure nets to zero.
The reverse trade (long perp, short spot via borrowing) collects negative funding but is harder to execute without a lending venue such as HyperLend on HyperEVM.
Cross-venue funding arbitrage exploits differences between exchanges: long the perp where funding is lower (or negative) and short where it is higher, harvesting the spread. The predictedFundings endpoint exists precisely for this comparison, and bots such as those covered in the Hyperliquid bot guide automate it. Both trades, with worked numbers, sit alongside eight other approaches in our Hyperliquid trading strategies guide.
Costs and risks to model before you try:
- Fees on both legs (0.045% taker or 0.015% maker on the perp, 0.07% / 0.04% on spot), which at elevated funding are recovered within a day or two, but at neutral funding take weeks.
- Funding can flip. A crowded-long market can turn negative within hours after a flush; the trade then pays instead of earning.
- Liquidation risk on the perp leg. Hold modest leverage (2x–3x) and keep spare margin; a hedged trade still liquidates if the perp leg's margin runs out.
- Basis risk between spot on one venue and the perp on another, plus bridge time and cost if you rebalance.
- ADL. In extreme moves a profitable short can be auto-deleveraged, breaking the hedge.
Risk note: funding arbitrage is not risk-free yield. Returns vary, and the leveraged leg can be liquidated. Nothing here is financial advice.
Funding rates as a trading signal
Even if you never arbitrage, funding shows you where the crowd is leaning:
- Fade extremes. Rates above 0.1% per 8h with rising OI have repeatedly marked local tops; deeply negative rates with rising OI, local bottoms.
- Confirm trends. A rally on neutral funding is healthier than one on extreme funding, because it is not built on leverage that must unwind.
- Time entries. If you want to be long a crowded market, entering right after a funding flush (when OI drops and rates normalize) is usually cheaper than paying peak funding.
- Track whales. When the largest addresses on the Hyperliquid wallet tracker flip sides, funding often follows within hours.
For step-by-step execution of any of these ideas, see how to trade on Hyperliquid.
Bottom line
Once you can read funding, you know what a position costs to hold and where the crowd is: Hyperliquid pays funding every hour, computed from the perp's average premium over an externally sourced oracle price plus a 0.01% per-8h base rate, clamped and capped at 4% per hour, with the mark price rather than the oracle governing liquidations. Read funding together with open interest and volume: crowded, high-funding, high-OI markets are where liquidation cascades start, and the data is free in the app, on Coinglass, Hyperdash, DefiLlama and the API. Funding arbitrage can turn the mechanism into income, but only after fees, flips and liquidation risk are accounted for. Master these three numbers and the Hyperliquid exchange becomes far easier to read.
Frequently Asked Questions
How often is funding paid on Hyperliquid?
Every hour, on the hour, so your perp stays close to its index and nobody can snipe a single settlement. Hyperliquid computes an 8-hour-equivalent funding rate from the average premium of the perp over the oracle price during the previous hour, then pays one eighth of it between longs and shorts. Payments go directly to and from position margin and appear in the Funding tab of the app.
What is the Hyperliquid funding rate formula?
Funding rate (8h) = average premium + clamp(0.01% − premium, −0.05%, +0.05%), where premium = (impact price − oracle price) / oracle price sampled every few seconds over the hour. The hourly payment is that rate divided by eight, multiplied by position notional at the oracle price, and capped at 4% per hour. See the formula section in this guide.
What is the difference between oracle price and mark price on Hyperliquid?
The split protects you from manipulation. The oracle price is a validator-weighted median of spot prices from major exchanges, updated about every three seconds, and is used for funding. The mark price blends the oracle, Hyperliquid's own order book mid and external perp prices, and is used for liquidations and unrealized P&L so that a single trade cannot trigger liquidations.
What is Hyperliquid's daily trading volume?
As of September 2026, Hyperliquid's 24-hour perp volume typically runs between $5 billion and $15 billion, with spikes above $20 billion during volatile sessions, giving it the largest share of on-chain perp volume. Open interest is usually $8–15 billion. Live figures are on the app's stats page, DefiLlama and Coinglass.
Where can I see Hyperliquid funding rates and open interest?
You can check every number for free. In the app, hover any market's info icon or open the Funding tab for your own payments. For cross-market views use Coinglass (funding, OI and liquidation data across exchanges), Hyperdash (Hyperliquid-specific OI, funding and whale positions), DefiLlama (volume and fees) and the /info API endpoints metaAndAssetCtxs, fundingHistory and predictedFundings.
Is funding rate arbitrage possible on Hyperliquid?
Yes. The classic cash-and-carry trade shorts a perp with high positive funding while holding the equivalent spot asset, collecting hourly payments. Hyperliquid's on-chain spot markets and Unit-bridged BTC, ETH and SOL let you do both legs in one account. Returns are not guaranteed: funding can flip negative, and the perp leg carries liquidation risk.
Ready to trade on the Hyperliquid app?
Open the official Hyperliquid DEX with our referral link and get a lifetime 4% discount on trading fees. No KYC, no gas fees, self-custody.
Open Hyperliquid App · Save 4%SIXPROSPERPaste the code in the referral field when you sign up (it must be applied before your first trade).
Disclaimer: This article is for educational purposes only and is not financial, investment or legal advice. Perpetual futures trading with leverage carries a high risk of loss. Read our full disclaimer.